Surety Bond Indemnity Agreements for California Contractors
Signing a bond agreement can put your business cash and personal assets at risk. A surety bond indemnity agreement can require you to repay claims, cover legal costs, and deposit collateral before a claim is resolved.
Your premium doesn't cap that financial exposure. The agreement's wording determines who owes money, when payment is due, and what the surety can recover.
Before you sign, understand the obligations below and have a qualified California attorney review the agreement.
What a surety bond indemnity agreement covers
The bond and the agreement
Your bond guarantees an obligation to another party. You're the principal, the surety company provides the guarantee, and the obligee receives its protection.
Surety bonding works like an extension of credit. During underwriting, the surety reviews your financial strength and ability to meet the bonded obligation because it expects repayment if it incurs covered losses.
That contract gives the surety contractual recovery rights against the people and companies who sign it. Those signers are called indemnitors.
Paying the premium doesn't transfer your business losses to the surety as liability insurance ordinarily would.
General versus bond-specific agreements
A general indemnity agreement, commonly called a GIA, usually covers a bonding relationship rather than one project. Depending on its terms, it may cover existing bonds, future bonds, renewals, and related obligations.
This arrangement is standard in construction bonding. The contractor, controlling owners, and often affiliated companies are ordinarily required to sign.
Smaller commercial bonds may instead include indemnity language within the application.
An "indemnity bond" is a financial guarantee. The indemnity agreement is the reimbursement contract supporting it. Don't treat those documents as interchangeable.
California bond requirements
California's official contractor bond requirements require a $25,000 contractor license bond issued by a surety licensed through the California Department of Insurance. That amount took effect January 1, 2023.
The bond protects eligible claimants against covered Contractors License Law violations. It doesn't provide a $25,000 operating cushion for your business.
Not every unpaid invoice, construction dispute, or property damage allegation automatically qualifies. Claimant eligibility and the legal basis for recovery matter.
Contractor LLCs have another requirement. CSLB's LLC licensing requirements include a separate $100,000 employee/worker bond in addition to the contractor license bond. A qualifying individual bond may also be required.
Those bonds have different purposes. Your indemnity obligations depend on which bonds the agreement covers, not simply the amount required for your license.
The applicable statutory rules appear in CSLB's 2026 contractor law reference. Bond claim rights come from those rules and the bond itself.
Our California contractor license bond guide explains the licensing side. A compliant bond keeps that requirement satisfied, but signing its indemnity agreement creates a separate repayment obligation.
Who signs and pays personally?
Owners and affiliated businesses
Most construction sureties require the principal business and its controlling owners to sign. Affiliates may also be included when their assets support the bonding program.
The business may be the principal, while an owner who signs individually may accept personal indemnity under the agreement. Signing for the company and signing individually are different acts.
Many agreements impose joint and several liability. Each indemnitor can be pursued for the full covered debt, not just an ownership percentage.
A 20% ownership interest doesn't automatically limit liability to 20%. Any liability cap must come from enforceable agreement language, not your ownership share.
Spouses and community property
Some sureties request spouse signatures. That isn't a universal California licensing requirement.
A spouse signing as an indemnitor may accept a direct repayment obligation. A signature acknowledging or consenting to an agreement can have a different effect.
California community property rules also matter without a spouse's signature. Family Code section 910 generally makes community property liable for debts incurred by either spouse during marriage.
Section 913 generally protects one spouse's separate property against the other spouse's debts. Exceptions, exemptions, account arrangements, and the actual undertaking affect the result.
Have your attorney review the signature capacity and marital-property exposure. A spouse's signature shouldn't be treated as routine paperwork.
Indemnification and enforcement costs
What you must reimburse
The indemnification provision usually requires reimbursement for losses and expenses connected to issuing the bonds.
This indemnification may include claim payments, investigation expenses, attorneys' fees, consultants' fees, and enforcement costs. Some provisions also cover liabilities before payment.
Your exposure can exceed the bond's stated amount. On a $25,000 license bond, a full $25,000 payout plus recoverable expenses can create a reimbursement demand above $25,000.
Read the covered-cost definitions carefully. The agreement may distinguish between actual payments, liabilities, reserves, and expenses.
Why legal fees matter
Under the American Rule, parties generally pay their own attorneys unless a contract or statute provides otherwise. GIA fee provisions can change that result.
California's Fidelity & Deposit Co. v. Whitson, 187 Cal.App.2d 751 (1960), upheld recovery under an express surety indemnity agreement. Recoverable amounts included a good-faith settlement payment, counsel fees, and costs.
Courts generally enforce clear GIA terms, subject to applicable defenses. Don't assume reimbursement stops at the claimant's payment.
Some agreements make the surety's payment records evidence of what you owe. Others include waivers or separate enforcement remedies.
Disputing a claim and defending a reimbursement lawsuit can become two separate expenses. Have your attorney identify both before signing.
The surety's right to settle
Your objection may not stop payment. Many GIAs give the surety sole and exclusive discretion to pay, settle, defend, or appeal claims.
That can allow settlement even when you believe the claimant is wrong. The surety may weigh legal expense, available evidence, and completion risk differently than you do.
Courts have generally treated decisions under broad settlement clauses as binding absent fraud or bad faith. The applicable standard depends on the agreement and governing law.
Disagreement alone doesn't establish bad faith.
Some agreements let indemnitors request litigation instead of settlement if they provide sufficient cash or collateral. This option can have strict notice requirements and funding conditions.
A right to request litigation may require you to fund the risk first. Objecting to settlement alone may not preserve that option.
Keep signed change orders, payment records, photographs, and job correspondence. Those records give the surety facts to evaluate rather than an unsupported denial.
For project claims, understanding performance and payment bond differences helps you identify which obligation is being disputed.
Collateral can be due immediately
Demands before a payout
A collateral clause can require cash or acceptable security immediately upon demand. The surety may demand it before paying any claim.
Depending on the wording, the demand can cover potential liability, claim reserves, anticipated expenses, or increases in those amounts.
That creates a separate cash-flow problem. You may still need to fund payroll, materials, and other projects while securing the surety's potential exposure.
Read how the amount is calculated and who determines acceptable collateral. A promise to provide equipment or property may not satisfy a clause requiring cash.
Refusing or challenging a demand
Refusing a contractually supported demand can lead to a lawsuit seeking an order to post collateral. Enforcement fees may also become recoverable under the agreement.
The available remedy depends on the contract and facts. A collateral obligation shouldn't be confused with a final determination that the underlying claimant is right.
Your attorney can assess whether the demand matches the agreement's trigger, calculation method, and notice requirements.
Also review how collateral is held, applied, and returned. Unused collateral may be returnable after covered exposure ends, but the timing and conditions depend on the agreement.
Don't count on immediate access to that money while claims remain unresolved.
Assignment and recovery rights
An assignment provision can give the surety rights to contract proceeds, subcontracts, equipment, materials, and other project assets.
The trigger matters. Some agreements activate those rights after default. Others use broader triggers, including notice of a claim.
The surety may use assigned funds to complete work, resolve payment obligations, or reduce its losses. That can affect your access to money needed for other jobs.
Assignment doesn't automatically override every lender lien or third-party right. Existing security interests, the agreement's wording, and applicable law affect priority and enforcement.
Review whether the provision covers only bonded projects or reaches other business assets. Also identify any power of attorney allowing the surety to act in your name.
Broad recovery rights can create conflicts with bank financing. Your attorney should compare the GIA with existing loan and security documents.
Understand what can be assigned before a disputed claim puts those rights into play.
Records, information, and cooperation
Books and third-party information
Many GIAs allow the surety to examine the principal's and indemnitors' books, records, accounts, and electronically stored information.
That may include job-cost reports, bank statements, tax returns, receivables, and personal financial records. Access can extend beyond documents relating to one claim.
Some agreements authorize banks, accountants, customers, or other third parties to provide information directly.
Review the scope, confidentiality provisions, and access procedures. Know which records you're agreeing to make available.
Your duty to cooperate
A cooperation clause may require you to respond to requests, preserve evidence, assist with investigations, and support claim defense or project completion.
Ignoring those requests can create another alleged breach of the agreement.
Keep project records organized and assign someone to handle surety communications. Missed deadlines and missing documents can weaken your position.
Cooperation doesn't require you to accept every allegation. Provide accurate facts and involve your attorney when requests affect disputed rights.
How a claim becomes your debt
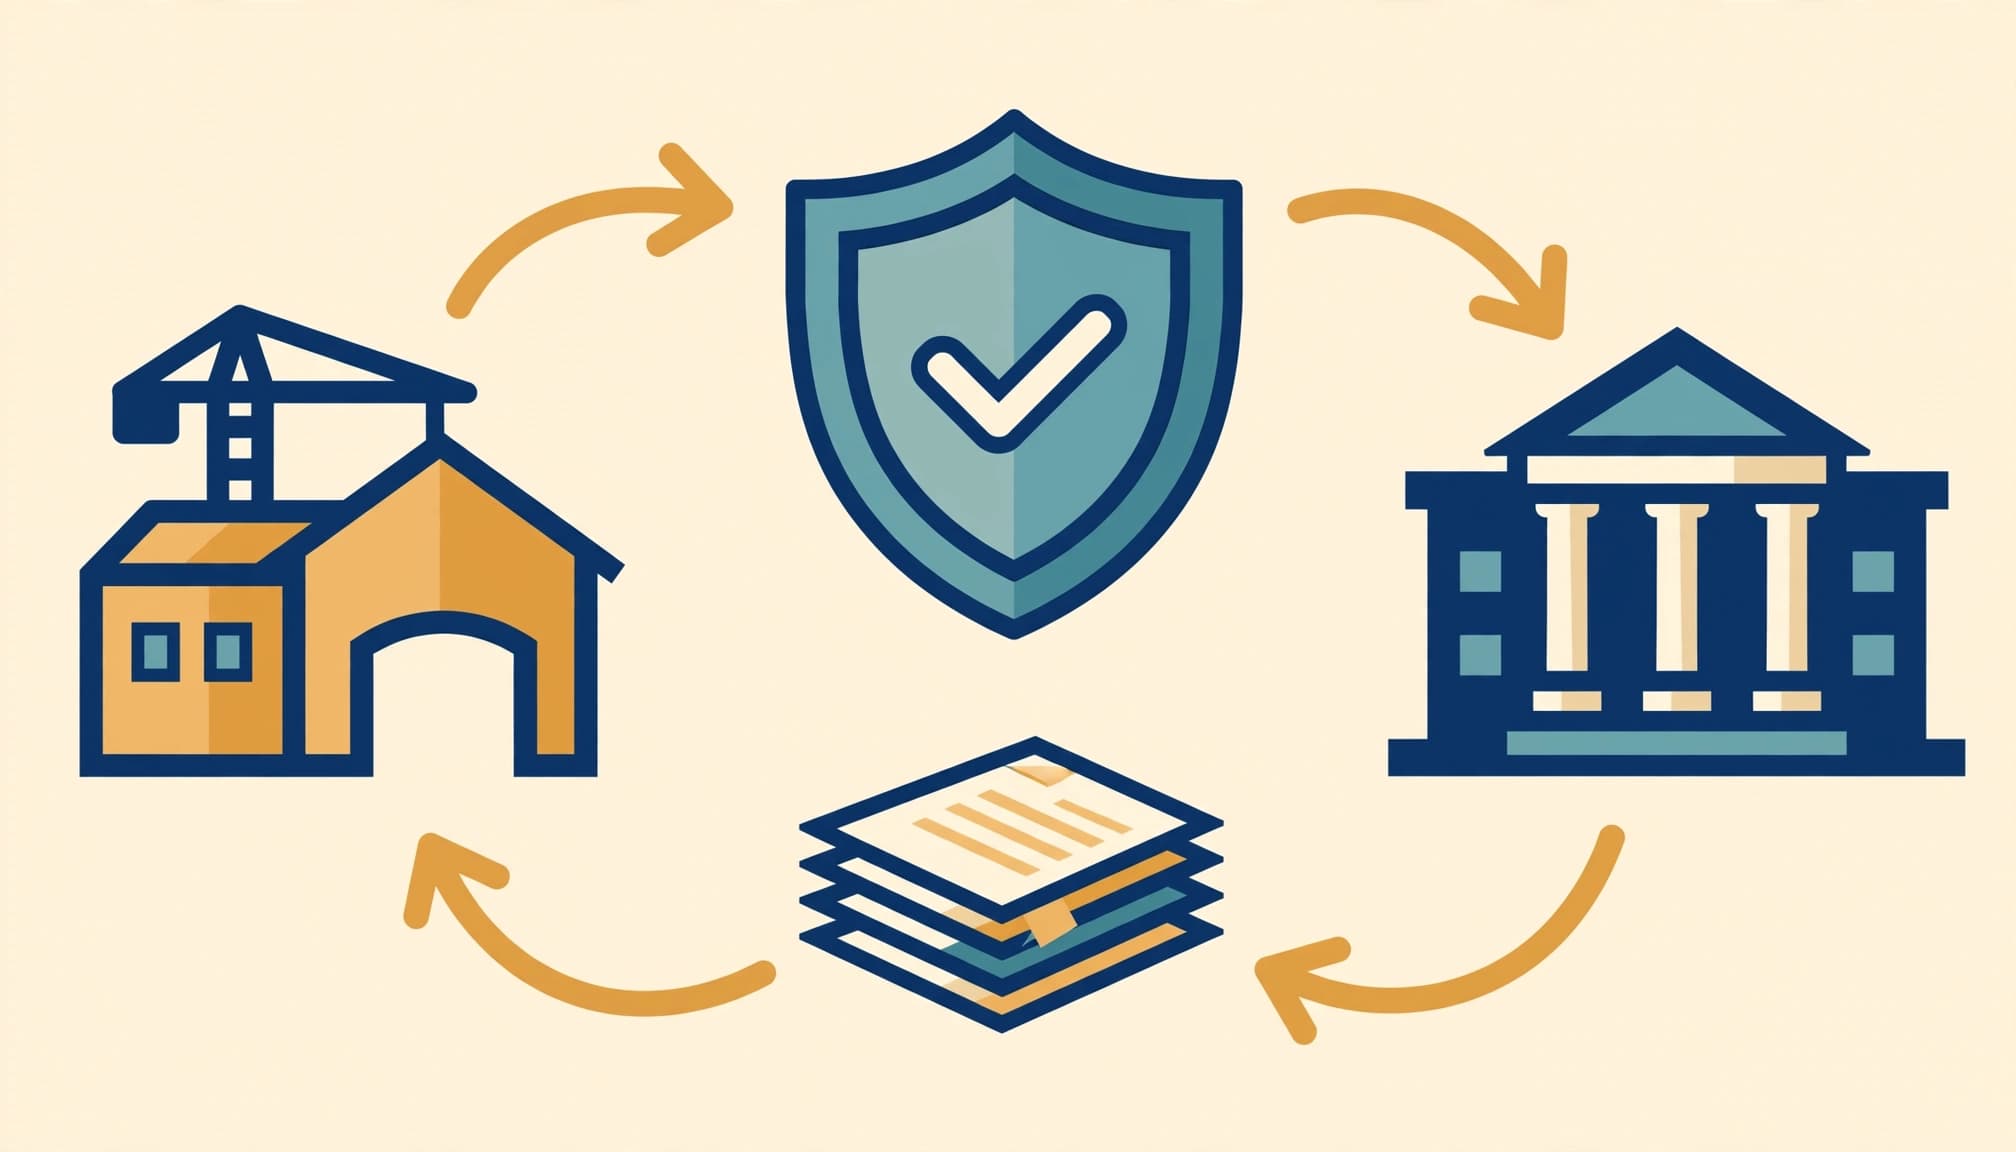
The bond claim and your indemnification obligation arise under separate documents. A claim can trigger obligations before the surety makes a payment.
- A claimant submits a demand under the bond. The surety reviews eligibility, supporting records, and the bonded obligation.
- The principal supplies records and a response when requested. Investigation or legal expenses may begin accumulating.
- A collateral clause may support a demand for security against potential losses and expenses.
- The surety decides whether to defend or settle under its contractual authority. Any option to request litigation must meet the agreement's conditions.
- After a covered payment, the surety may require indemnitors to reimburse the surety and may use its enforcement or assignment rights under the agreement.
For a $25,000 license bond, a full-limit payment can mean $25,000 owed back before recoverable fees are added. Joint and several liability may allow collection of the entire debt from one indemnitor, depending on the agreement.
That doesn't mean the surety can collect the same debt repeatedly from every signer. The agreement controls each indemnitor's liability and whether the surety must divide its demand among them.
Respond early. Preserve records, understand collateral deadlines, and have counsel address disputed obligations before expenses grow.
Premiums and applying for bonds
Premium isn't your liability limit
The premium pays for issuing the guarantee. It doesn't buy forgiveness of a reimbursement debt.
NFP's published indemnity-bond overview gives broad premium benchmarks of about 1% of the bond amount for good credit. It cites roughly 3% to 4% for spotty credit.
Those figures aren't universal California contractor rates. Bond type, credit, financial condition, project size, and underwriting requirements affect pricing.
Our standard California contractor license bonds range from $139 to $2,500 per year. That price is separate from any later collateral or reimbursement obligation.
Different products, different terms
Commercial bonds often involve personal indemnity and continuous coverage. Construction programs commonly use broader GIAs across multiple projects.
Fidelity coverage may include subrogation rights and aggregate limits. It addresses different risks and shouldn't be treated as interchangeable with contractor surety bonding.
To apply, provide the required business, license, ownership, and financial information. Larger project programs typically require more financial detail than routine license bonds.
Our construction project bonding guide covers the project-specific options. Choose the bond first, then review the indemnity supporting it.
What to review before signing
Start with scope, signers, and triggers. These determine whose assets are exposed and how quickly obligations can arise.
Give your attorney the complete agreement, application, bond form, and any related security documents. Reviewing only the signature page misses the provisions that create liability.
Focus your review on three areas:
- Identify every indemnitor and whether each person signs individually, for a business, or only in another stated capacity.
- Review covered bonds, reimbursable expenses, settlement authority, collateral deadlines, the assignment provision and its triggers, and information access.
- Examine termination procedures, future-bond coverage, ownership changes, and the conditions for obtaining a written release.
Sureties often resist changes to standard GIAs. Still, your attorney can request narrower affiliate coverage, clearer collateral calculations, notice requirements, or limits on future obligations.
Whether a surety accepts those changes depends on underwriting and the requested bond program. Don't assume an oral assurance changes a signed agreement.
Selling the business or leaving ownership doesn't automatically release personal indemnity. Written termination may stop coverage for certain future bonds while leaving existing exposure in place.
A signed agreement can support greater contractor bonding capacity, but capacity comes with obligations.
This is general information, not legal advice about your agreement or assets. Consult a qualified California attorney before signing, especially when spouses or affiliated companies are included.
Key takeaways
- Your premium and bond amount don't necessarily limit reimbursement, legal expenses, or personal exposure.
- Broad GIAs can allow settlement over your objection and collateral demands before the surety pays a claim.
- Personal signatures, joint and several liability, assignment provisions, and future-bond coverage deserve attorney review.
The practical payoff is clear: understand the financial commitment before it affects payroll, project funds, or personal assets.
Frequently asked questions
Who is the surety?
The surety is the company issuing the bond and backing the guaranteed obligation. We're the agency helping you obtain the bond, not the surety itself.
The obligee receives the guarantee's protection. Your reimbursement duties run to the surety under the indemnity agreement.
Does general liability pay this debt?
Don't assume it does. General liability coverage and surety indemnity address different obligations.
An underlying incident may raise insurance questions, but the promise to reimburse a surety doesn't automatically become a covered insurance claim. Policy language and the facts control coverage.
Does every claim suspend my license?
No. Filing a claim doesn't itself establish that your license must be suspended.
Failure to maintain the required bond can lead to suspension. Claim payments, cancellation, judgments, or other circumstances may create separate licensing issues. Keep the bond requirement and the disputed claim distinct.
Sign with your exposure understood
A surety bond helps you meet licensing or project requirements. Its indemnity agreement can commit business funds and personal assets well beyond the premium.
Review the repayment and collateral obligations with a qualified California attorney before signing. Understand who is liable and how that liability ends.
Need a California contractor bond? Get quote today, and our team can help you choose the bond for your licensing or project needs.